OVERVIEW
POPULAR ARTICLES

In our 21st October blog (India’s New Kings & Queens Are Flourishing in Small Town India) we showed how a new class of business families is flourishing in small town India. In our view of the most dependable routes into this class runs through running auto showrooms. Over the past decade the domestic revenue of India’s listed auto makers has compounded at 11% a year, and the dealers who sell and service these vehicles have ridden that growth. We estimate that India’s auto dealers now earn about Rs 14,000 crore of net profit a year – more than double the FY16 level – and have earned roughly around Rs 1 lakh crore cumulatively over the decade. The average dealer makes around Rs 80 lakhs of PAT a year, 7x the income of an average middle-class taxpayer. A typical car dealer runs around 3 dealerships and makes about Rs 2.5 crore of PAT/yr. The money is made less in selling vehicles than in servicing them, more in small towns than in metros, and more by families who add outlets, generation after generation. To see how a dealership family is built, we went further into small town Maharashtra where Jackie Chaturani and his extended family have grown a single two-wheeler shop into a chain of Royal Enfield dealerships stretching from Mumbai to the Gujarat border. Please visit invest.marcellus.in if you would like to invest with us in a rapidly changing India.
“The journey of a thousand miles begins with a single step.” – Lao Tzu, Chinese philosopher
Where we left off: the new Kings & Queens of small-town India
In India’s New Kings & Queens Are Flourishing in Small Towns, we showed that the number of Indians declaring more than Rs 1 crore of income has risen about seven-fold in the last twelve years. Companies earning Rs 50–500 crore of profit have more than doubled in number, the growth has come from independent promoters rather than old business houses, and it has been fastest away from the big metros. We highlighted the Adhikaris of Boisar, a family that has grown from supplying building materials into hospitals, schools, logistics – and an Indian Oil fuel station on the state highway.
That fuel station is a clue. In our view some of the most reliable building blocks of small-town family wealth are franchises granted by large national companies – a fuel pump, a cement or FMCG distributorship, and above all, an auto dealership. In this blog we follow the money from one of India’s most consistently growing industries to the families who sit at the end of its supply chain.
Ten years of 11% growth in India’s auto sector
Over the past decade the domestic revenue of India’s 15 listed auto makers – passenger vehicles, two- and three-wheelers, trucks and tractors – has grown from about Rs 2.35 lakh crore in FY16 to Rs 6.72 lakh crore in FY26, a compound annual growth rate of 11.1%. That growth came through demonetisation, GST, the switch to BS-VI emission norms, a credit crunch and Covid. Passenger vehicles led the way at 12.9% a year on the back of India’s shift to SUVs, followed by tractors at 10.9%.
Exhibit 1: India’s auto makers have compounded domestic revenue at 11% a year for a decade
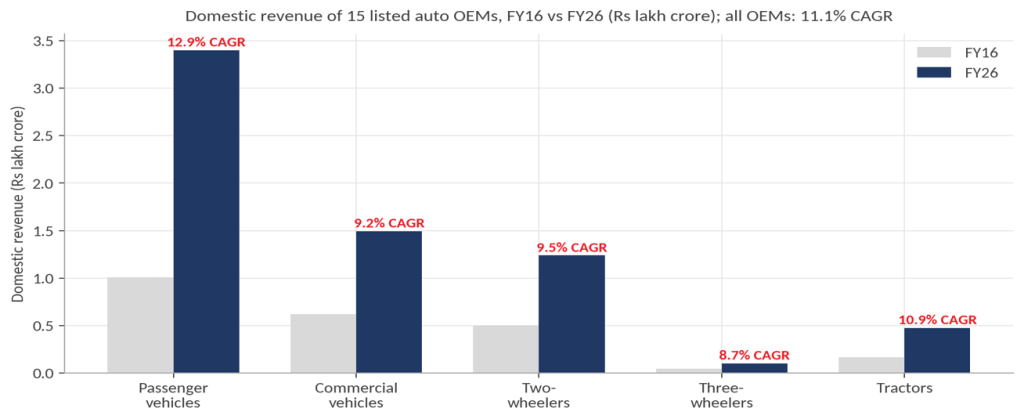
Source: Marcellus Investment Managers; ACE Equity standalone revenue (Marcellus research database), company annual reports. 15 listed OEMs; exports removed using annual-report geographic disclosures or export volumes; Tata Motors CV and PV combined across the 2025 demerger. FY = year ending March. The securities mentioned in this blog are quoted as examples and not as recommendations.
So, who has pocketed the gains?
A sector growing at 11% a year for a decade creates a lot of wealth. Much of it accrues to the shareholders of the auto makers. But how has this growth translated into wealth for the new Kings & Queens of small-town India – the families who do not own listed shares in Maruti or Mahindra, but who own something just as valuable in their towns?
The answer: a nationwide web of auto dealerships
Nearly every vehicle sold in India passes through a dealer. India has about 15,000 dealer businesses running more than 30,000 outlets, according to the Federation of Automobile Dealers Associations (FADA); including the many rural tractor and two-wheeler dealers outside FADA, we estimate the total number of dealers at about 18,000. Almost all of them are privately owned, most by local business families.
To size their earnings, we built a bottom-up model of the average dealer in each segment. We start from the auto makers’ domestic revenue, add the dealer’s margin on each vehicle (which FADA’s survey puts at roughly 3.7–5% of the price), add service, spare parts, accessories and insurance and finance commissions, and deduct customer discounts, operating costs, depreciation, interest and tax. We calibrated the result to India’s two listed dealer groups, Landmark Cars and Popular Vehicles. These are estimates rather than reported figures, but they give a sense of scale.
The answer is striking. India’s auto dealers earned about Rs 13,800 crore of net profit in FY26, up from about Rs 6,400 crore in FY16 – roughly Rs 1 lakh crore of PAT earned cumulatively over the decade. Before interest, depreciation and tax, they generate about Rs 40,000 crore a year of profit. Car dealers account for nearly three-quarters of that profit pool.
Just to put that Rs 14K crore of annual PAT earned by the auto dealers into perspective, L&T – an industrial giant with market cap of Rs 5 lakh crore (Rs 5 trillion or $50bn) – has PAT of around Rs 15K crore.
Exhibit 2: India’s auto dealers earn about Rs 14,000 crore of net profit a year
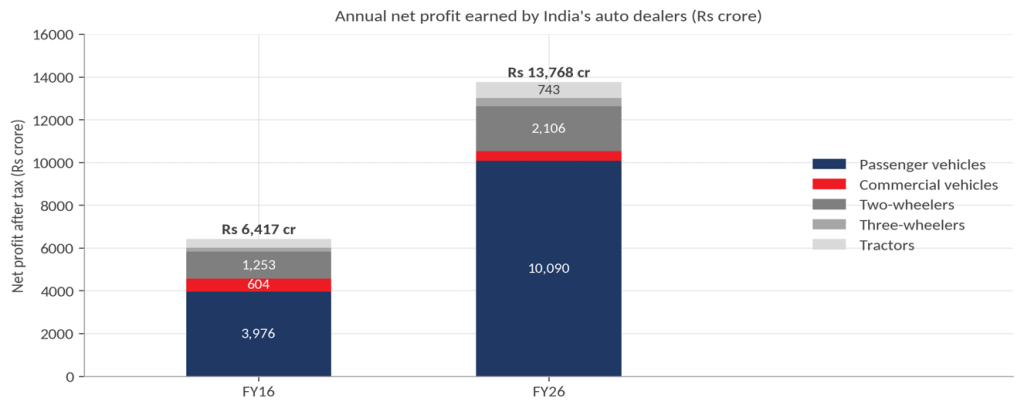
Source: Marcellus Investment Managers estimates (dealer economics model built on ACE Equity standalone OEM data, company annual reports, FADA, SIAM and TMA). Dealer businesses estimated at ~12,000 in FY16 and ~18,000 in FY26 (FADA: 10,000+ dealers in 2016; 15,000 dealer businesses and 30,000+ outlets in 2026, plus non-member rural dealers). Profit after interest and tax, including service income.
Spread across these businesses, the average dealer earns about Rs 76 lakh a year of PAT. The average car dealer – who typically runs about three outlets – makes about Rs 2.5 crore/ year (similar to the compensation received by a Board Director of a BSE 100 listed company). Two-wheeler, three-wheeler, truck and tractor dealers are smaller businesses, earning Rs 17–38 lakh a year. Commercial vehicle dealers are the exception: their profits per dealer have roughly halved, squeezed by thin margins, heavy discounting on fleet deals and rising costs.
Exhibit 3: The average car dealer earns about Rs 2.5 crore a year
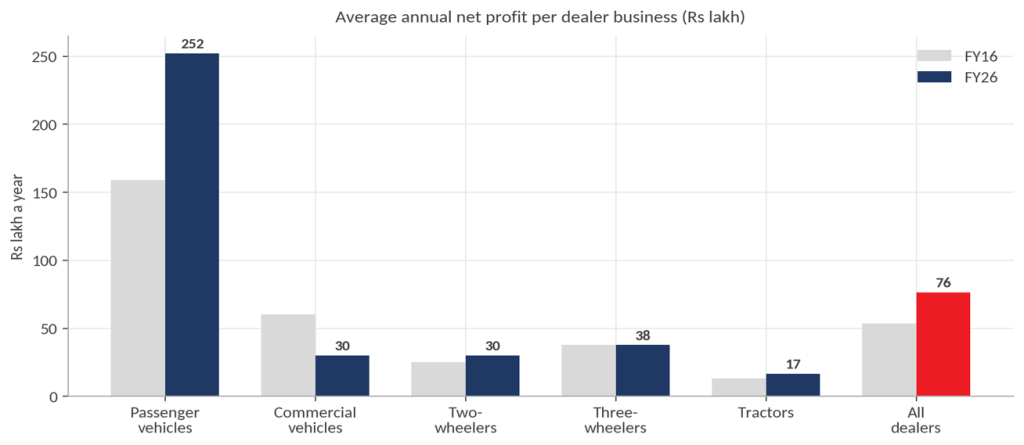
Source: Marcellus Investment Managers estimates (dealer economics model built on ACE Equity standalone OEM data, company annual reports, FADA, SIAM and TMA). Average dealer business; per-dealer figures depend on the estimated number of dealers in each segment.
Set against the middle class we wrote about in our last blog, these are princely sums. The average dealer family earns about seven times what the average middle-class taxpayer does; a car dealer earns about 24 times as much; and a car dealer group with ten outlets, about 100 times. It is no surprise that every district town in India has dealership-owning families among its most prominent.
Exhibit 4: A car dealer earns about 24 times the income of an average middle-class taxpayer
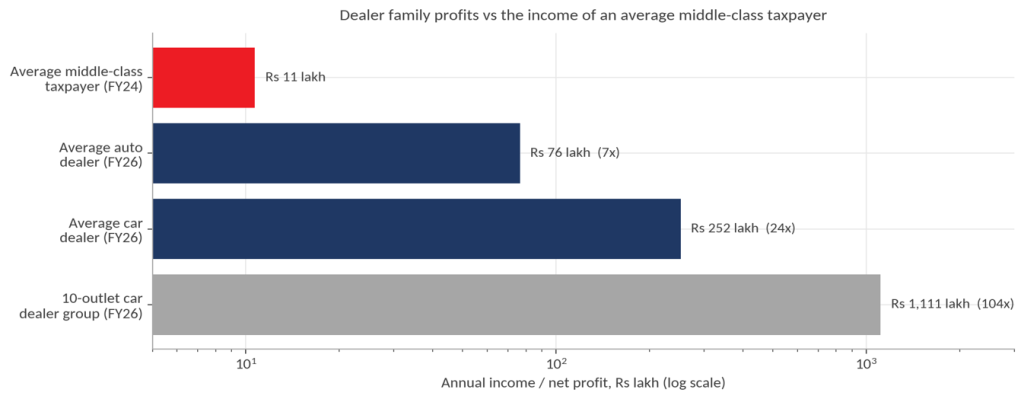
Source: Marcellus Investment Managers; Income Tax Department data as analysed in India’s Middle Class is Losing Ground to the Rich & the Poor and Breakpoint (2026) for the average income of taxpayers earning Rs 5 lakh–Rs 1 crore in FY24; dealer figures are Marcellus estimates of net profit for FY26. Business profit and personal income are not strictly comparable; dealer families also earn rent, salaries and interest from their dealerships that are not captured here.
Why are auto dealerships so lucrative?
On the face of it, selling cars is a thin business. The dealer’s margin on a new vehicle has not improved in ten years, and much of it is given away to customers as discounts. Yet three features turn a dealership into a durable engine of family wealth.
- After-sales service is where the money is – especially in small towns
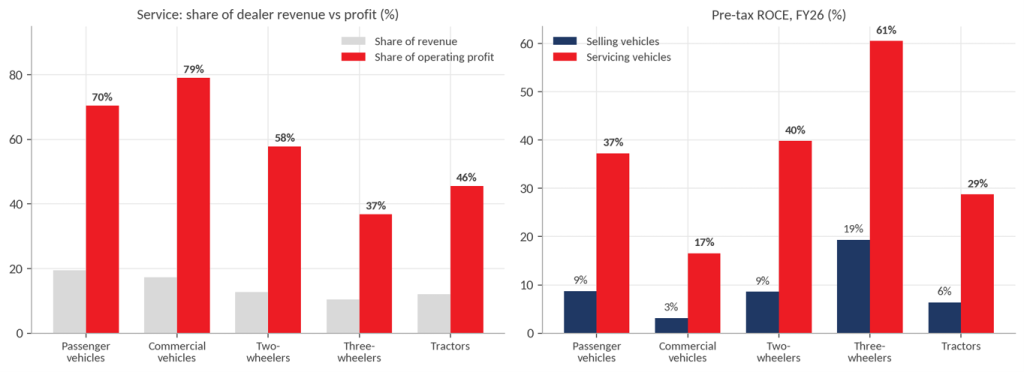
Selling a vehicle earns a dealer a gross margin of 3–5% and a net margin close to zero. Servicing it earns a gross margin of 30–40%, from labour, spare parts, accessories, body-shop work paid for by insurers, and commissions on loans and insurance. As a result, service makes up only about a fifth of a car dealer’s revenue but about 70% of its operating profit, and nearly 80% for a truck dealer. Our estimates show that a car dealer earns a return on capital of about 37% on its workshops against about 9% on its showrooms. Each car sold is the start of an annuity: the owner typically returns for servicing for five to seven years.
Exhibit 5: Service is a small slice of dealer revenue but most of the profit – and earns about four times the return
Source: Marcellus Investment Managers estimates (dealer economics model built on ACE Equity standalone OEM data, company annual reports, FADA, SIAM and TMA). FY26. Service = workshop labour, spare parts, accessories and finance/insurance commissions. ROCE = earnings before interest and tax ÷ capital employed, excluding leased land and buildings; calibrated to Landmark Cars’ after-sales margin of ~20% and new-vehicle margin of ~2%.
Location matters as much. In the metros, dealers pay high rents and salaries, face several outlets of the same brand in one city and have to discount heavily to win customers. Maruti’s own premium Nexa network, built around big cities, has carried the burden of lower returns because of high real estate, employee and operating costs, which is why Maruti began building smaller-format showrooms for small towns. Mayank Pareek, who built Maruti’s rural sales network, put it simply: rural customers are much more profitable than city customers. Small-town dealers often own their land, pay less for staff, face less competition from same-brand outlets and – with many customers paying cash – give away less of their margin.
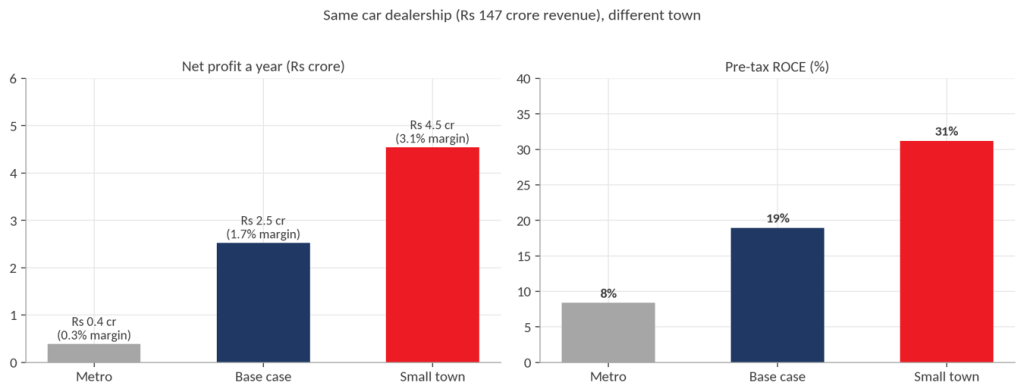
To illustrate, we took the same car dealership – with around Rs 150 crore of annual revenue – and placed it in a metro and a small town. Higher costs and deeper discounts in the metro reduce its net profit to under Rs 0.5 crore, while in a small town the same business earns about Rs 4.5 crore and a return on capital of about 31%. It is no coincidence that India’s two listed dealer groups, both with large metro exposure, earn low returns.
Exhibit 6: The same car dealership is far more profitable in a small town than in a metro
Source: Marcellus Investment Managers estimates (dealer economics model built on ACE Equity standalone OEM data, company annual reports, FADA, SIAM and TMA). Illustrative. Base case = average FY26 car dealer. Metro assumes 50% of the dealer margin given away as discounts (base 40%, small town 30%), 25% higher showroom costs and 15% higher workshop costs (small town: 20% and 15% lower), and 30% higher fixed capital (small town: 30% lower). Revenue held constant.
This helps explain why growth in auto sales has tilted towards smaller towns. Rural retail sales grew 7.6% in FY25 against 5.1% in cities, and in April 2026 rural retail grew 20.4% against 7.1% in urban India, according to FADA. Maruti alone has more than doubled its sales outlets over the decade, from about 2,150 to 4,600, with a large part of the additions aimed at smaller towns.
- Scaling from one dealership to many lifts profitability
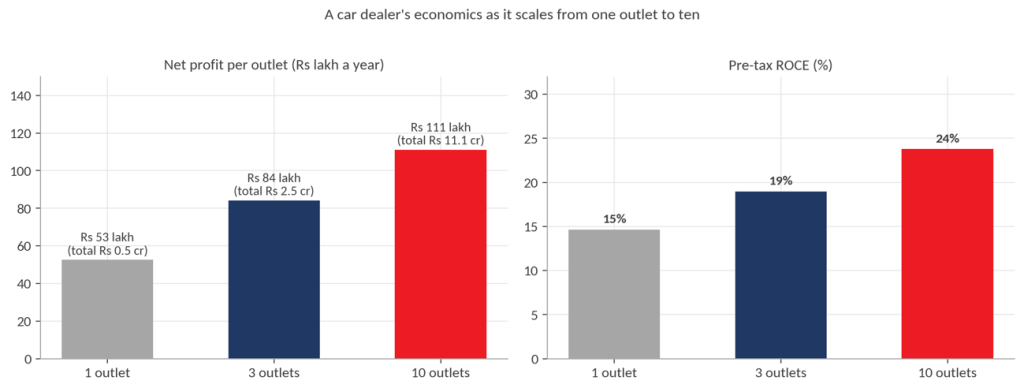
A family that runs one showroom bears the full cost of an owner’s office, accounts, HR and IT systems on a single outlet’s sales. A family that runs ten spreads those costs across ten outlets, pools its inventory so that it needs fewer days of stock, borrows at better rates and earns higher volume incentives from the auto maker. Auto makers, in turn, prefer to award new territories and satellite outlets to existing dealers who have performed. In our illustration, net profit per outlet roughly doubles and the return on capital rises from about 15% to about 24% as a car dealer grows from one outlet to ten. A ten-outlet car dealer group earns about Rs 11 crore a year [comparable to the compensation of a Board Director of a Nifty50 company].
Exhibit 7: A car dealer’s profit per outlet roughly doubles as it grows from one outlet to ten
Source: Marcellus Investment Managers estimates (dealer economics model built on ACE Equity standalone OEM data, company annual reports, FADA, SIAM and TMA). Illustrative. 3-outlet case = average FY26 car dealer. Assumes group overheads of Rs 0.6 crore (1 outlet), Rs 1.2 crore (3) and Rs 2.5 crore (10); vehicle inventory of 50, 45 and 38 days; borrowing costs of 10.5%, 9.5% and 8.75%; and auto-maker incentives of 1.2%, 1.5% and 1.8% of vehicle sales.
- Each new generation gets its own dealership
In a business family, every generation brings more heirs. Dealerships offer a ready way to give each of them a substantial, self-contained business: a new brand, a new district or a new satellite network, run by a son, daughter or nephew, financed by the cash flows of the existing outlets and backed by the family’s standing with the auto maker. Over decades, this turns a single showroom into a regional dynasty.
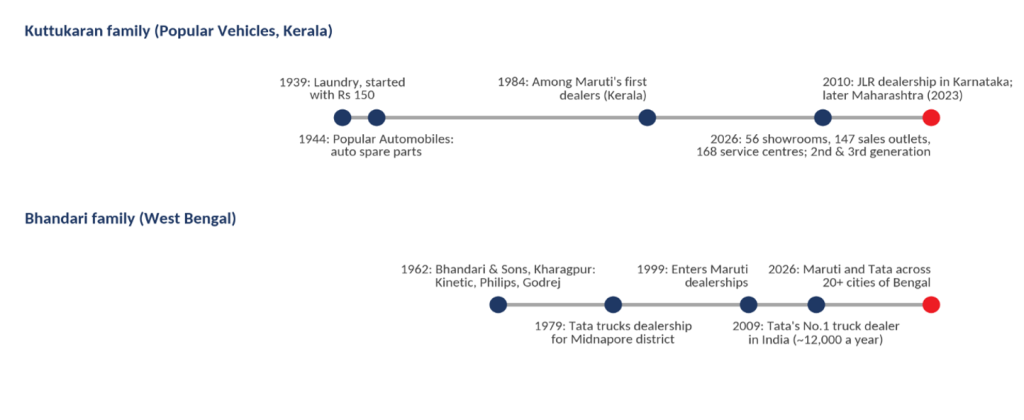
The Kuttukaran family of Kerala began with a laundry in 1939, entered the auto parts business in 1944 and became one of Maruti’s first dealers in 1984. With the second and third generations at the helm, its group now runs 56 sales showrooms and 168 service centres across several states.
The Bhandari family arrived in Kharagpur in Bengal in 1905 as traders, took its first Tata dealership in 1979 and its first Maruti dealership in 1999; three generations on, it runs more than 150 touchpoints in West Bengal with about Rs 3,000 crore of revenue.
Exhibit 8: Two dealer families, decades of compounding
Source: Marcellus Investment Managers; Popular Vehicles annual report and company website; ISB case study ‘Managing Change at the Kuttukaran Group’; public profile of the Bhandari group (2026). Mention of these companies is for illustration only and is not a recommendation.
These families share the traits that helped the Adhikaris of Boisar: capital and land from an earlier trading business, which spares them the rent and interest that sink new entrants; a trader’s discipline over stock and cash; and relationships with local bankers, financiers, insurers and fleet buyers built over decades. Few outsiders try to break in – a car dealership today ties up roughly Rs 25–30 crore of capital – which is precisely why the business keeps rewarding those already inside it.
The risks: what can go wrong
As with any profitable enterprise in a free-market economy, dealerships carry risks. Three stand out.
- Abrupt regulatory changes
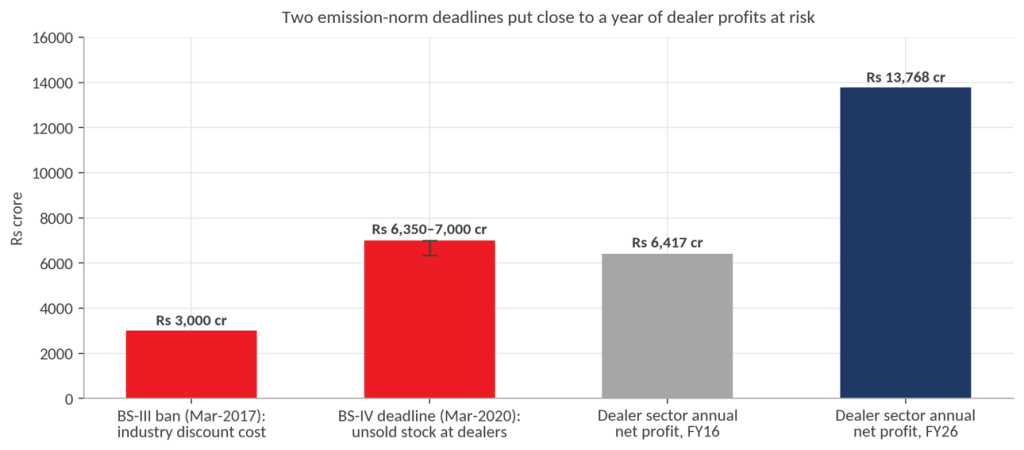
A dealer’s biggest asset is its stock of unsold vehicles, which makes it acutely exposed to sudden rule changes. In March 2017 the Supreme Court banned the sale of BS-III vehicles from 1 April, forcing discounts that CRISIL estimated cost the industry about Rs 3,000 crore. Three years later, the switch from BS-IV to BS-VI norms on 1 April 2020 collided with the Covid lockdown: dealers were left holding an estimated Rs 6,350–7,000 crore of BS-IV stock – including some 15,000 cars, 12,000 commercial vehicles and seven lakh two-wheelers – and the Supreme Court allowed only 10% of it to be sold after the lockdown. That is close to a full year of the entire sector’s profits.
Exhibit 9: Two emission-norm deadlines put close to a year of dealer profits at risk
Source: Marcellus Investment Managers; CRISIL via Motilal Oswal (BS-III, 2017); Autocar Professional and FADA submissions to the Supreme Court (BS-IV, March 2020); Marcellus estimates for dealer profits. The BS-III figure is the estimated industry-wide cost of discounts, much of it borne by manufacturers.
- Economic cycles
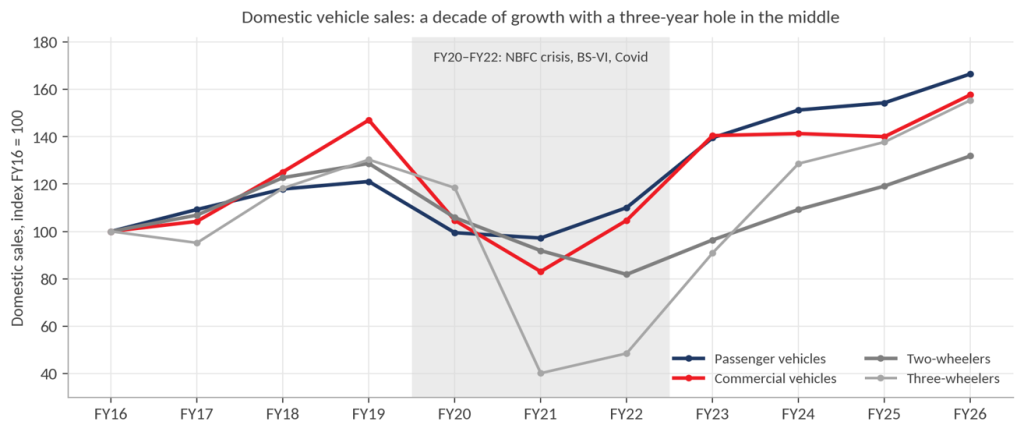
Dealers carry fixed costs and borrowed inventory, so a downturn hits them harder than the auto makers. Between FY19 and FY22, India’s auto market went through the NBFC credit crunch, the BS-VI transition and Covid. Car sales did not regain their FY19 level until FY23, two-wheeler sales fell by more than a third and three-wheeler sales collapsed by two-thirds. In 2019 alone, around 300 car and bike outlets shut down, and only about 30% of dealers were estimated to be profitable.
Exhibit 10: A decade of growth with a three-year hole in the middle
Source: Marcellus Investment Managers; SIAM (domestic sales) and TMA (tractors, not shown); FY17–FY24 compiled from SIAM annual data. Index of domestic unit sales, FY16 = 100.
- Large networks squeezing smaller ones
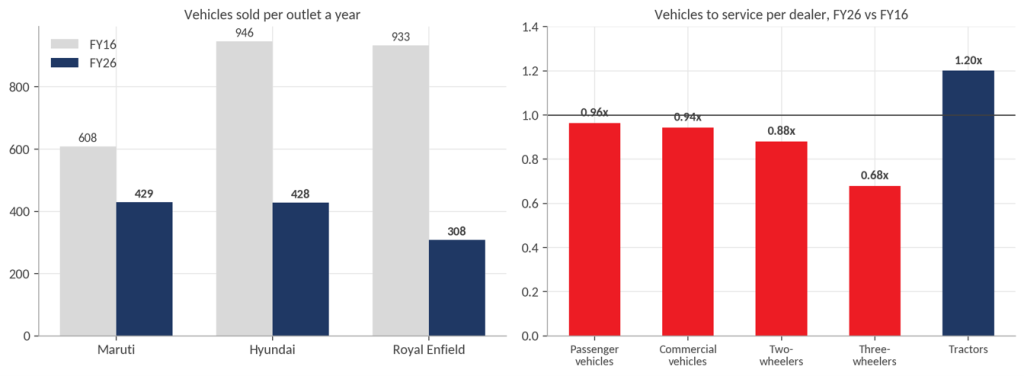
Auto makers have expanded their dealer networks faster than the market. Maruti more than doubled its sales outlets over the decade, Hyundai nearly tripled its sales points and Royal Enfield added hundreds of small studio stores. As a result, the average outlet now sells far fewer vehicles than it did in FY16, and in most segments each dealer has fewer vehicles to service. The families that have added outlets have captured this expansion; the single-outlet dealer that stayed small has seen its throughput – and its profits – squeezed by larger groups selling the same brand in the same district.
Exhibit 11: Outlets sell fewer vehicles each, and most dealers have fewer vehicles to service
Source: Marcellus Investment Managers; company outlet disclosures (Maruti: ~2,150 outlets FY16, 4,600 FY26; Hyundai: 512 FY16, 1,366 FY26; Royal Enfield: ~525 FY16, ~3,600 FY26 including studio stores); SIAM and TMA sales; Marcellus estimates of the serviceable installed base (last eight years of sales weighted by the share still serviced at a dealer) and dealer counts.
We went further into Boisar
In our previous blog we met the Adhikaris of Boisar, the industrial town 100 km north of Mumbai. This time, to see how a dealership family is built, we went further into Boisar. Deep inside the Tarapur MIDC industrial estate is Sonith Motors, the area’s Royal Enfield showroom and service centre, run and partly owned by Jackie Chaturani. We have visited him with our team several times since 2016.
Jackie’s brother in law, Mr. Jairaj Bhagchandani entered the two-wheeler trade in 1996 with a multi-brand showroom and took its first Royal Enfield dealership in 2004 – before Siddhartha Lal’s turnaround made the brand one of India’s most profitable motorcycle makers. “Then Sid Lal arrived… and we just kept growing,” Jackie told us. In 2016 Mr. Bhagchandani got an offer from Royal Enfield to open a store in Boisar; Mr. Bhagchandani did a recce, saw an industrial area that would keep growing, and opened in late 2016.
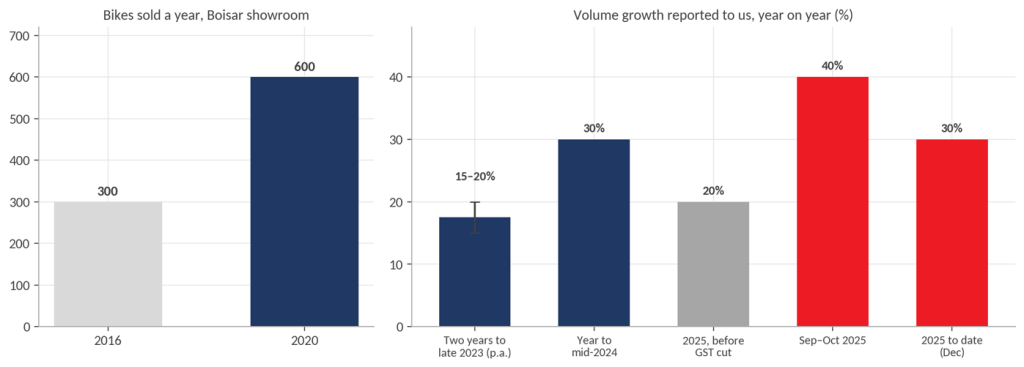
When we visited Jackie’s Boisar showroom in late 2020, the showroom was a compact 1,000 sq ft space with four bikes on display, beautifully fitted out to Royal Enfield’s specifications – and it had doubled its sales from about 300 bikes a year to 600 in four years, while the town’s Bajaj showroom had just shut down. He rides a Royal Enfield Himalayan himself: “I don’t think you can sell an RE to a customer without driving one yourself.”
Growth has continued on every visit since: 15–20% a year to late 2023, about 30% in the year to mid-2024 and about 30% in 2025, when the GST cut on bikes of up to 350cc pushed September–October sales up 40% and lifted the 350cc share of his sales from 85% to 92–95%. The extras that make dealerships lucrative have grown faster still: genuine accessories per bike have risen from Rs 3,500–5,000 to about Rs 12,000, apparel per bike has doubled, almost every buyer now takes accessories and about half buy on credit, mostly through HDFC Bank and IDFC First Bank. His customers are a cross-section of the new Boisar – local Adivasi and fishing families with land and savings, officers at Tata, JSW and Viraj Steel earning Rs 5–50 lakh a year, migrant workers and college students.
Exhibit 12: Bhagchandani’s Boisar showroom: sales doubled in four years and have kept growing
Source: Marcellus Investment Managers channel checks with Jackie Chaturani (2016, late 2020, late 2023, mid-2024, December 2025). Growth rates are as reported to us.
Mr. Bhagchandani is an exemplar of the quintessential Octopus story, one which follows each of the three features that make auto dealerships lucrative. It has scaled from one shop to many outlets, adding studio stores around its flagships (Dahanu in 2021). It has moved into smaller, faster-growing towns when the manufacturer came calling. And it has given successive family members their own units: company filings and Royal Enfield’s dealer listings show a web of family companies with common partners and directors – Riya Motors (2008), Soniya Motors (2009), Sonith Motors (an LLP since 2019), So Innovative Motors (2020), Soriya Bikes (2021) and Soniya Motorrad (2025) – running at least nine Royal Enfield showrooms and service points from Bhandup in Mumbai through Thane, Navi Mumbai and Bhiwandi to Boisar and Dahanu. Soniya Motors alone reports annual turnover in the Rs 25–100 crore band. Not every tentacle survives – two entities set up in 2011 and 2022 were discontinued by Mr. Bhagchandani and the family intentionally – but a new one has appeared every couple of years.
Exhibit 13: The family’s Royal Enfield footprint
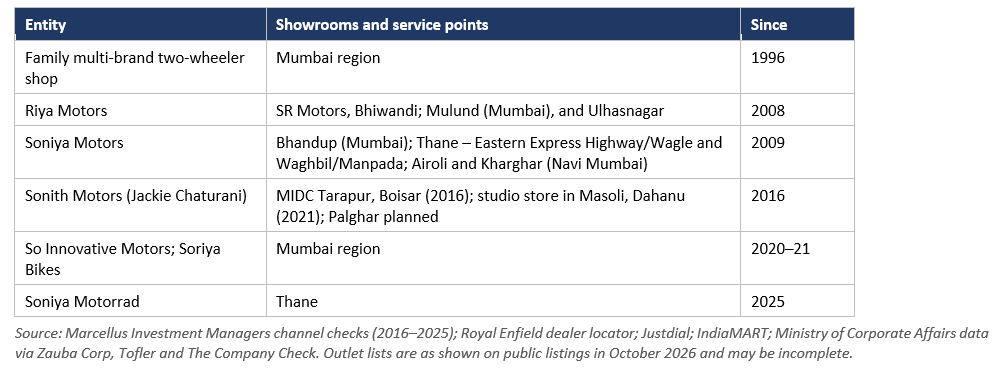
Source: Marcellus Investment Managers channel checks (2016–2025); Royal Enfield dealer locator; Justdial; IndiaMART; Ministry of Corporate Affairs data via Zauba Corp, Tofler and The Company Check. Outlet lists are as shown on public listings in October 2026 and may be incomplete.
Exhibit 14: A two-wheeler Octopus
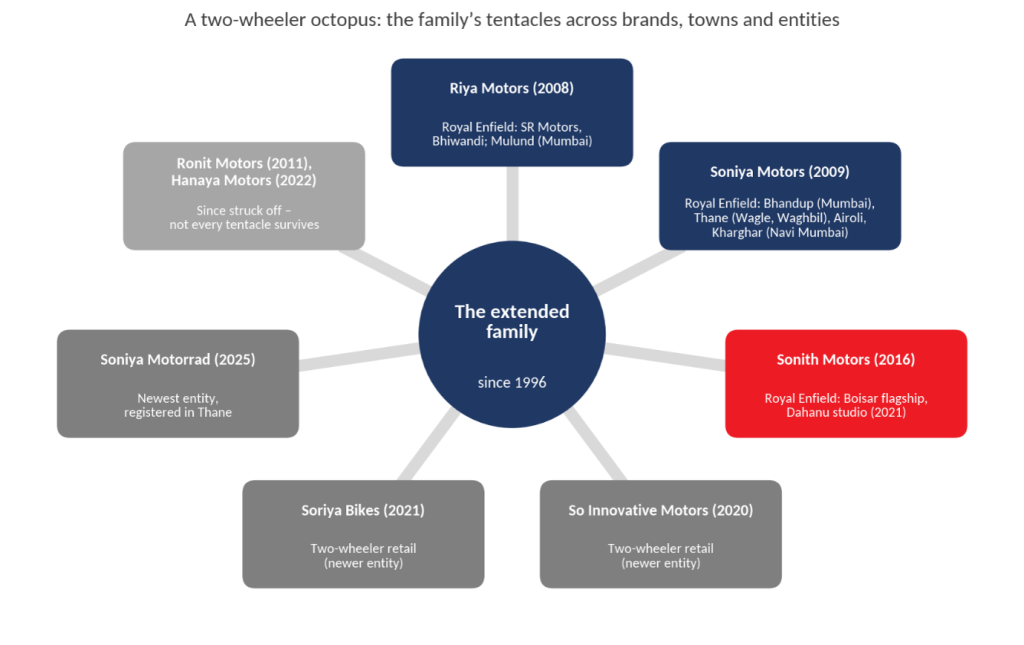
Source: Marcellus Investment Managers; Royal Enfield dealer locator; Ministry of Corporate Affairs data via Zauba Corp, Tofler and The Company Check; channel checks with Jackie Chaturani. Years are incorporation or opening dates.
Like the Adhikaris, the family also consumes the services the new class prizes: Jackie’s children study at the IB school that opened in the area after Covid. On our rough estimates, Mr. Bhagchandani, the owner and originator of this family enterprise, generates an income of approximately Rs. 1 crore a year; and across the extended family’s network, the stores’ earnings would comfortably place several of its members among the 3.24 lakh Indians declaring more than Rs 1 crore of income.
India: a dealership in every district, a dynasty in every dealership
The auto sector’s decade of 11% growth has created wealth well beyond the stock market. A large part of it has flowed to some 18,000 dealer businesses – most of them family-owned, many of them in India’s smaller towns – that together earn about Rs 14,000 crore a year. The model rewards those with capital, land, local relationships and the patience to scale across districts and generations, and it punishes the over-leveraged and the sub-scale when regulation or the economy turns. In that sense, the auto dealership is the quintessential tentacle of the small-town ‘Octopus’ we described in Behold the Leviathan: a franchise from a national brand, run with local trust, funding the family’s next venture. Every district headquarters and highway town in India has its own Jackie Chaturani. Through extensive travel and meetings with dealers, bankers, local businesses and listed companies, we at Marcellus seek to keep abreast of a rapidly changing country. You could benefit from our endeavour by investing with us. If you would like to learn more about our investment approach, which focuses on companies we assess to be clean and well-managed, please visit invest.marcellus.in or scan the QR code below.
# This tool is designed to help users explore products and asset allocation guidance; it does not constitute a formal financial plan or investment advice
The stocks mentioned above may form part of Marcellus’ portfolio. Marcellus, its clients, and/or its employees may therefore have an interest in the said stock(s).
Click Here for details about our regulatory registration and licensing information
The above material is neither investment research, nor investment advice. Marcellus does not seek payment for or business from this material/email in any shape or form. Marcellus Investment Managers Private Limited (“Marcellus”) is regulated by the Securities and Exchange Board of India (“SEBI”) as a provider of Portfolio Management Services. Marcellus is also a US Securities & Exchange Commission (“US SEC”) registered Investment Advisor and is regulated by the International Financial Services Centres Authority (IFSCA) as a Fund Management Entity. No content of this publication including the performance related information is verified by SEBI, IFSCA or US SEC. If any recipient or reader of this material is based outside India and USA, please note that Marcellus may not be regulated in such jurisdiction and this material is not a solicitation to use Marcellus’s services. The PMS strategy, Category III AIF products and IFSCA retail schemes are distinct offerings with different regulatory frameworks, risk profiles, fee structures and investment thresholds. Investors should refer to product-specific documents for details before investing. All recipients of this material must, before dealing and or transacting in any of the products and services referred to in this material, make their own investigation and seek appropriate professional advice. Investments in securities market are subject to market risks. Read all the related documents carefully before investing. Past performance is not indicative of future results. Marcellus and/or its associates, the authors of this material (including their relatives) may have financial interest by way of investments in the companies covered in this material. Marcellus does not receive compensation from the companies for their coverage in this material. This material may contain confidential or proprietary information and user shall take prior written consent from Marcellus before any reproduction in any form. Clients have an option to be on-boarded directly by the Portfolio Manager without intermediation of persons engaged in distribution services. Investments in securities markets are subject to market risks and there is no assurance that any investment objective will be achieved.